Managing money with two incomes should feel like a superpower, yet many dual-income households find themselves wondering where all the money went. Earning two paychecks often brings higher combined purchasing power, but it can also introduce lifestyle creep, complex expense-splitting debates, and communication hurdles.
A realistic household budget isn’t about placing harsh restrictions on your lifestyle. Instead, it is a collaborative roadmap designed to align two distinct incomes with your shared family goals, reducing financial friction and building long-term security.
Step 1: Combine, Keep Separate, or Hybrid? Choosing Your Financial System
Before diving into numbers, you and your partner need to agree on how you will manage your money. There is no single correct model; the best system is the one that fosters complete transparency and mutual trust.
- Fully Combined Accounts: All income flows into a single joint checking and savings account, and all expenses are paid from it. This model maximizes transparency and works well for couples with high trust and aligned spending styles.
- Separate Accounts with Proportional Splitting: Both partners keep individual accounts and contribute a set percentage (often proportional to their respective salaries) into a joint account to cover shared household expenses. This preserves a sense of financial independence.
- The Hybrid System: A popular middle ground where couples maintain personal spending money accounts for guilt-free individual purchases, while all major household bills, savings, and investments are handled through a joint account.
Step 2: Calculate True Net Income and Audit Current Spending
Budgeting fails when it is built on hypothetical numbers. Start by looking past your gross combined salaries and calculating your true net take-home pay—the money that actually hits your accounts after taxes, health insurance premiums, and pre-tax retirement contributions are deducted.
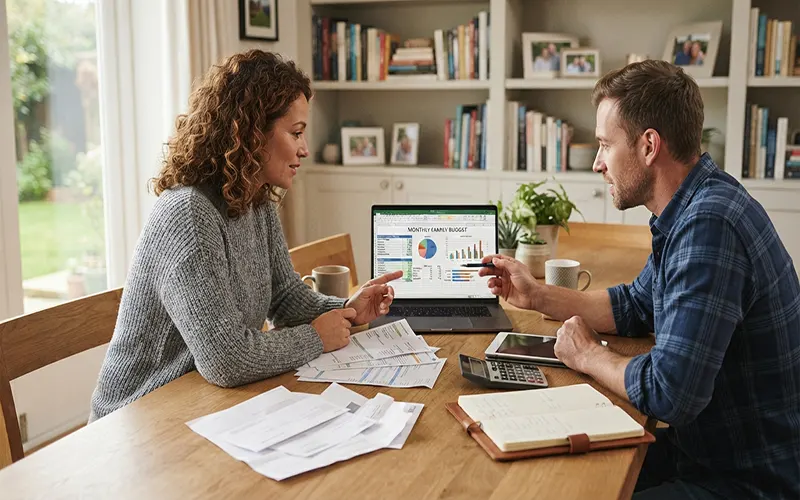
Next, conduct a joint spending audit. Sit down together with the last three months of bank and credit card statements. Categorize your spending into three buckets:
- Fixed Expenses: Mortgage or rent, utilities, insurance, auto loans, and essential childcare.
- Variable Costs: Groceries, gas, household supplies, and routine medical care.
- Money Leaks: Forgotten subscription services, frequent impulse dining out, and convenience purchases that add up quickly.
Seeing the raw data together provides a neutral baseline, preventing finger-pointing and revealing where your cash is actually flowing.
Step 3: Build the Framework (The 50/30/20 Rule Adapted for Two Incomes)
With your net income and baseline spending clear, adopt a flexible budgeting framework. The classic 50/30/20 rule is easily adapted for dual-income households to keep things balanced:
- 50% for Needs: Cover your essential obligations. For dual-income families, this heavily features housing, utilities, groceries, insurance, and critical career-enabling expenses like professional clothing, commuting costs, and reliable childcare or daycare.
- 30% for Wants: Allocate room for lifestyle enjoyment. This includes family entertainment, dining out, hobbies, and vacations. Because you both work hard, having designated “wants” money prevents burnout and budget resentment.
- 20% for Savings and Debt: Direct this portion toward building an emergency fund (aiming for 3 to 6 months of combined expenses), maxing out retirement accounts, funding college savings plans, and paying down high-interest debt.
Step 4: Automate and Establish Regular Money Dates
Human willpower is a finite resource, which is why manual budgeting often fails. The secret to long-term consistency is automation.
Set up automatic bill payments for all fixed household expenses. Simultaneously, program automatic transfers to move money into your savings and investment accounts the day after your paychecks hit. When your savings happen in the background, you never have to “find” the willpower to save.
Finally, establish a monthly “Money Date.” Grab coffee or cook a nice dinner together to review your budget progress, adjust for upcoming seasonal expenses (like holidays or back-to-school shopping), and celebrate financial wins without judgment or stress.
Creating a household budget as a dual-income family is an act of teamwork. By choosing a financial system that builds trust, auditing your real spending habits, adapting the 50/30/20 framework, and automating your savings, you can turn your combined earning power into true peace of mind.