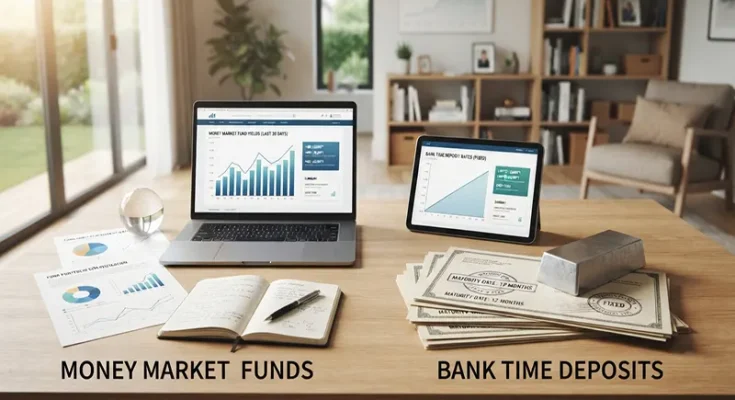
Money Market Mutual Funds vs. Bank Time Deposits: Yields and Liquidity Comparison

Money Market Mutual Funds vs. Bank Time Deposits: Yields and Liquidity Comparison

When managing conservative cash savings, conservative savers face a classic financial puzzle: how do you balance maximizing your interest yield with maintaining immediate access to your funds? Leaving cash sitting in a low-yield checking account means losing purchasing power to inflation, but locking money away blindly can lead to severe penalties if an emergency arises.

To solve this dilemma, savers typically look at two primary vehicles: Money Market Mutual Funds (MMFs) and Bank Time Deposits (Certificates of Deposit or fixed deposits). While both options prioritize the safety of your principal investment, they differ drastically in their liquidity rules, yield flexibility, and underlying safety structures.

Defining the Contenders

Before comparing performance, it is vital to understand how each financial vehicle is structured and where it lives:

  • Money Market Mutual Funds: These are investment products offered by brokerage firms and mutual fund companies. They pool investor capital to purchase ultra-safe, short-term
Money Market Mutual Funds vs. Bank Time Deposits: Yields and Liquidity Comparison Continue Reading >>>
Step-by-Step Guide to Financing a Car with No Down Payment

Step-by-Step Guide to Financing a Car with No Down Payment

When you need a reliable vehicle to get to work or manage family obligations, waiting months to save up a hefty cash reserve isn’t always an option. The appeal of zero-down car financing is undeniable—it allows you to drive off the lot immediately without depleting your current bank account.

However, financing a car with no down payment comes with significant financial trade-offs. While it is entirely possible, it requires careful navigation to avoid falling into debt traps, paying exorbitant interest, or landing underwater on your loan.

Understanding the Reality of No-Down-Payment Auto Loans

When you secure a zero-down auto loan, you are borrowing 100% of the vehicle’s purchase price. Furthermore, if you choose to roll your sales tax, title, registration, and dealer fees into the financing package, you will instantly borrow even more than the car is actually worth.

This immediately introduces the risk of being “upside-down” or “underwater” on …

Step-by-Step Guide to Financing a Car with No Down Payment Continue Reading >>>