Choosing where to secure your auto loan is one of the most financially impactful decisions you will make during the car-buying process. Selecting the right lender can save you thousands of dollars in interest over the life of the loan, while the wrong choice can trap you in a high-cost contract.
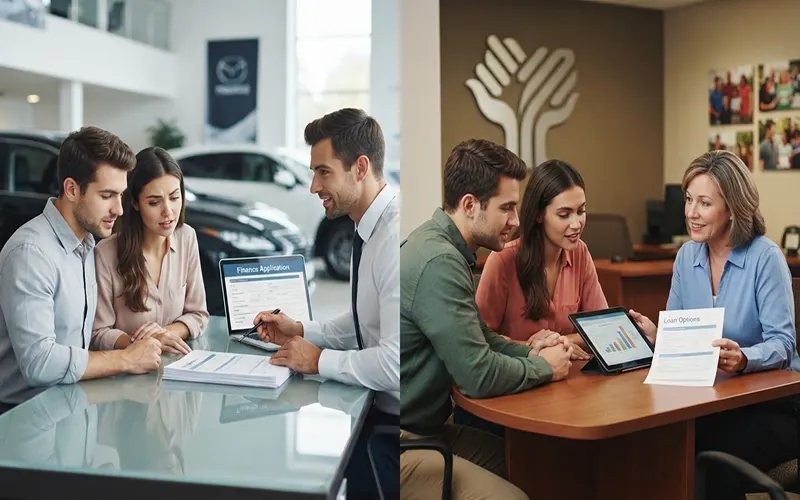
When it comes to financing a vehicle, buyers typically weigh two primary contenders: dealership financing (including manufacturer captive lenders and third-party dealer networks) and credit union financing. Neither option is universally “better.” The right choice depends on a careful balance between promotional incentives, interest rates, overall convenience, and your personal credit profile.
Deep Dive Into Dealership Financing
Dealership financing refers to the loans arranged directly through the car dealership’s finance and insurance (F&I) office. Dealerships don’t lend money themselves; instead, they submit your application to a network of third-party banks or to the manufacturer’s captive finance arm (such as Toyota Financial Services, Ford Credit, or BMW Financial Services).
The Pros of Dealership Financing:
- Access to Promotional Rates: This is the dealership’s superpower. Manufacturers frequently subsidize special financing deals—such as 0% or low-APR incentives—for highly qualified buyers purchasing specific new car models.
- Convenient “One-Stop Shop”: You can negotiate the price of the car and finalize your financing in the exact same afternoon without coordinating between multiple financial institutions.
- Speed and Flexibility: Dealership software connects with dozens of lenders instantly, making it easier for buyers with varying credit scores to secure a same-day approval.
The Cons of Dealership Financing:
- The Dealer Reserve (Interest Markups): Dealerships often add a “dealer reserve” markup—increasing the interest rate offered by the bank by 1% to 2%—to pocket extra profit.
- High-Pressure Upsells: F&I offices are notorious for pushing expensive add-ons, extended warranties, and gap insurance into your monthly financing package.
- Payment Packing: Shady dealers may focus entirely on manipulating the monthly payment rather than the total loan cost, hiding inflated interest rates behind longer loan terms.
Deep Dive Into Credit Union Financing
Credit unions are member-owned, non-profit financial cooperatives. Because their primary goal is serving their members rather than generating corporate profits, they typically return earnings to consumers in the form of lower loan rates and fewer fees.
The Pros of Credit Union Financing:
- Consistently Lower Everyday Rates: For standard new and used car loans, credit unions almost always beat the everyday standard rates offered by traditional commercial banks and dealerships.
- Transparent, Personalized Service: Credit unions offer a consultative experience, helping you understand your loan structure without high-pressure sales tactics.
- Pre-Approval Power: Walking onto a car lot with an official pre-approval letter from a credit union gives you cash-in-hand status, turning you into a cash buyer during negotiations.
The Cons of Credit Union Financing:
- Membership Requirements: You must qualify for membership based on specific criteria, such as where you live, work, worship, or your association with certain organizations.
- Slower Turnaround Times: While digital applications have improved drastically, getting pre-approved can sometimes take a couple of business days compared to the instant dealership process.
- Lack of Manufacturer Subsidies: Credit unions cannot match manufacturer-sponsored 0% APR promotional financing programs on brand-new vehicles.
Head-to-Head Comparison: Cost, Flexibility, and Experience
When deciding between the two, evaluating them across three critical dimensions can help clarify your strategy:
- Rate & Total Borrowing Cost: If you are buying a brand-new car and qualify for a manufacturer’s 0% or low-APR promotional incentive, dealership financing wins on cost every single time. However, for standard used car purchases, credit unions consistently provide lower base APRs.
- Negotiation Leverage: Having a credit union pre-approval in your pocket shifts the psychological power dynamic. The dealer knows they must beat your credit union’s rate to earn your financing business, keeping them honest.
- Convenience vs. Control: Dealership financing is undeniably more convenient, but credit union financing gives you absolute control and transparency over your loan terms before you ever see a vehicle.
Strategic Playbook: How to Play Both Sides for the Best Deal
Smart car buyers don’t choose just one option blindly—they leverage both systems against each other to secure the absolute best terms. Follow this three-step playbook:
- Get Pre-Approved First: Before stepping foot on a dealership lot, apply for an auto loan with a local credit union. This establishes your baseline “floor” interest rate and shows you exactly what monthly payment you can afford.
- Let the Dealer Compete: When negotiating the purchase, keep your credit union pre-approval under wraps until you have agreed on an out-the-door price for the vehicle. Once it’s time to talk financing, show the dealer your rate and challenge them to beat it.
- Read the Fine Print: Compare the final financing contracts side-by-side. Look closely at the total cost of borrowing, any hidden origination fees, and check whether the lender charges prepayment penalties if you decide to refinance later.
Is dealership financing better than a credit union? The answer depends entirely on the car you are buying. Credit unions generally win on everyday low rates, transparency, and consumer advocacy for used car purchases. Dealership financing wins decisively when manufacturer-sponsored promotional rates apply to a new vehicle.